Home loan eligibility & process for pre-launch villas
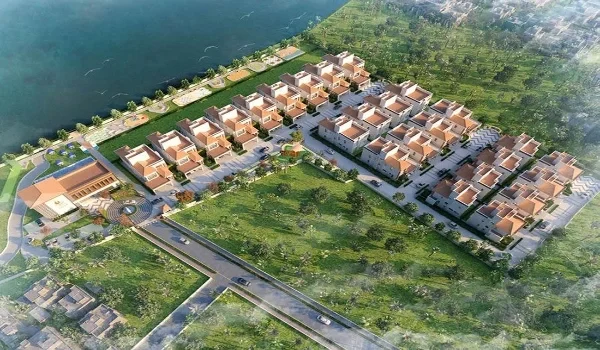
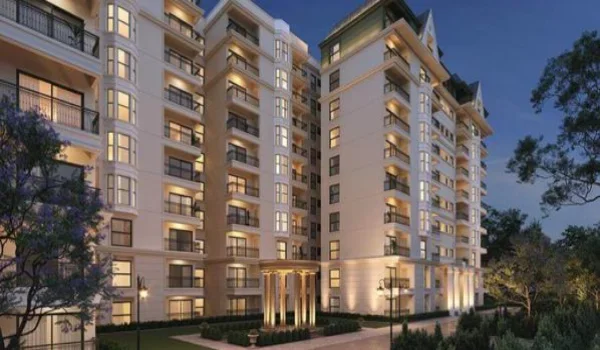
Getting a home loan for a pre-launch villa is possible. But before you pay, check the project, builder, loan rules, and your loan eligibility. Banks usually look at your income, credit score, age, current loans, and EMI payment ability. They also check the villa’s land papers, approvals, RERA details, and construction status. Checking all this early can help you set your budget and avoid delays later. Checking these details early can help buyers plan their budget and avoid delays during the buying process. A great example of an early-stage project is Nambiar Aranyaka, a 76-acre forest-themed luxury villa community by Nambiar Builders located in Bilwaradahalli along Bannerghatta Road, South Bangalore. Because pre-launch loans release money in small parts as construction moves forward, knowing how the bank approves your file helps you plan your cash flow and avoid costly delays.
Project Profile: Nambiar Aranyaka
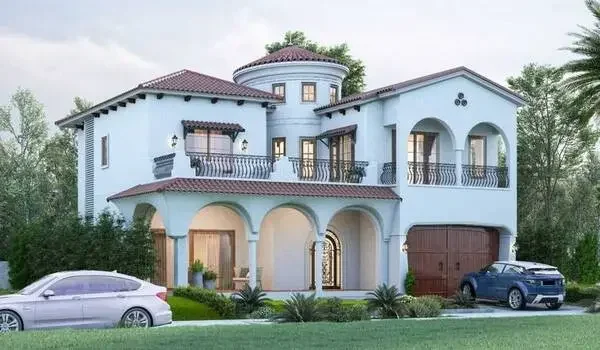
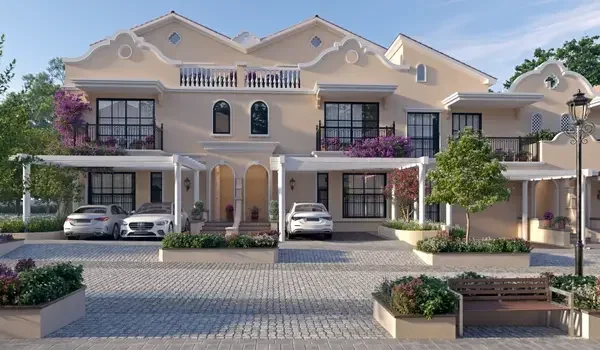
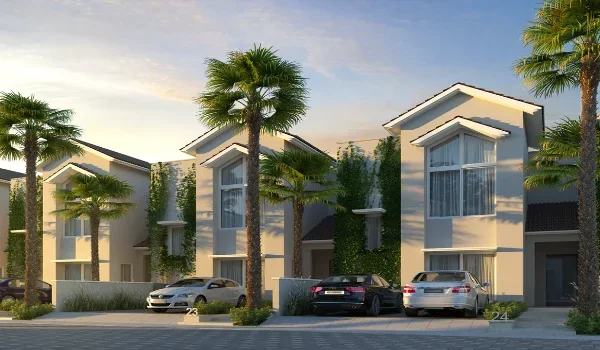
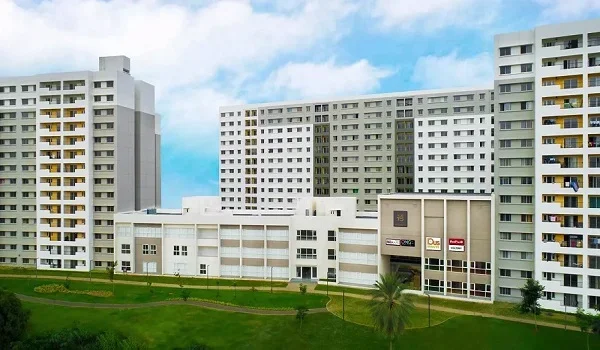
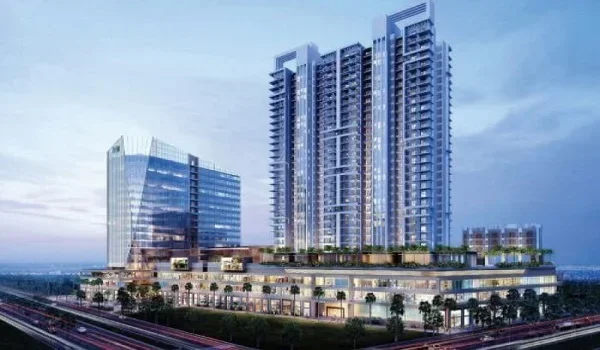
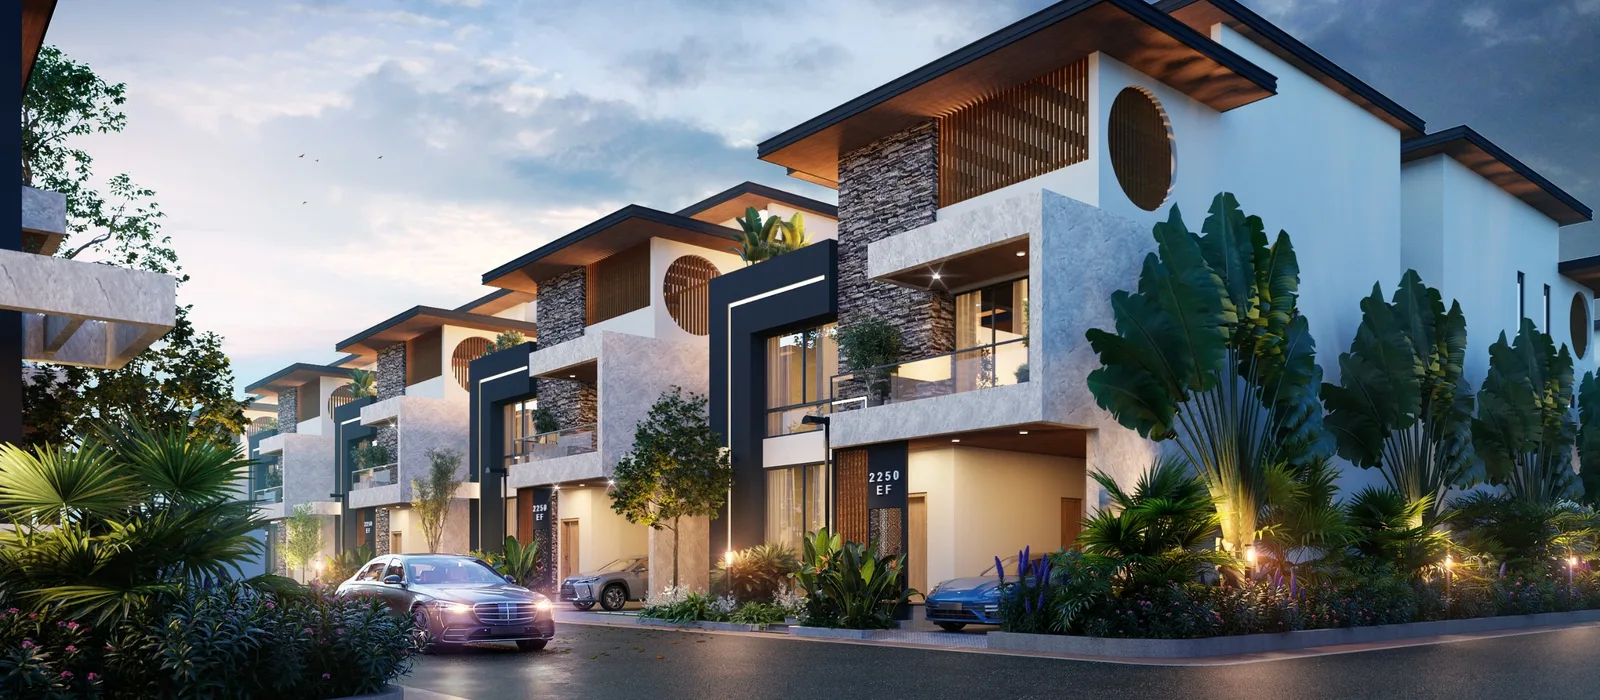
Nambiar Aranyaka is a forest-themed villa project in Bilwaradahalli, near Bannerghatta Road in South Bangalore. The project covers 76 acres, while Phase 1 is spread across 36 acres. It has 298 luxury independent villas, with each villa built as a full G+2 home.
| Key Details | Project Fact Sheet |
|---|---|
| Developer | Nambiar Builders |
| Location | Bilwaradahalli, Bannerghatta Road, South Bangalore |
| Official Launch Date | Pre-launch Phase (Expected Launch: Sept/Oct 2026) |
| Expected Possession Date | December 2030 / January 2031 |
| RERA Status | K-RERA Registration in Process |
| Total Land Area | 76 Acres Master Plan (Phase 1: 36 Acres) |
| Total Villa Units | 298 Independent Units (Phase 1) |
| Structure & Layouts | G+2 Floors | 4 BHK & 5 BHK Configurations |
| Unit Saleable Area | 3,732 sq. ft. to 4,638 sq. ft. |
| Base Price Range | ₹5.48 Cr (35x55 ft) to ₹7.29 Cr (Flagship layouts) |
What Is a Pre-Launch Villa?
A pre-launch villa is a house you buy before construction starts on the site. Developers sell these units early to raise money, so they offer lower entry prices to attract buyers.
As the project is still at an early stage, some building documents and structures may not be ready yet. Buyers should check all land approvals, project documents, and bank loan options before paying the booking amount.
Can You Get a Home Loan for a Pre-Launch Villa?
Yes, you can get a home loan for a pre-launch villa if the bank approves the project papers. Banks check the builder's track record and safety approvals before putting the project on their approved list.
The bank will not give you the full loan amount at once. Instead, they release money in small steps as the builder finishes each phase of the building work.
Home Loan Eligibility Criteria for Pre-Launch Villas
Banks decide your loan amount by assessing your financial health and debt risk.
1. Income and Job Stability
Your monthly income helps the bank see if you can pay your EMI on time. Salaried buyers usually need to provide salary slips and bank statements. Business owners may need to submit tax returns and business financial records.
| Applicant Type | Key Financial Documents |
|---|---|
| Salaried Employees | 3 Months' Payslips, 6 Months' Bank Statements, Form 16 |
| Self-Employed | 3 Years' ITR, Audited Financial Statements, Business Proofs |
2. Credit Score (CIBIL Profile)
A CIBIL credit score of 750 or higher gets you lower interest rates and faster loan approvals. Banks check your old bill records to see if you pay your debts on time.
3. Current Loans and Debt (FOIR)
Banks look at your current personal loans, car loans, and credit card dues. If you already spend a lot of cash on active EMIs, the bank will reduce your new loan limit.
4. Age and Repayment Time
Young buyers may get a longer loan term, sometimes up to 30 years or until retirement age. A longer loan term can lower your monthly EMI, but you may pay more interest over the years.
5. Down Payment Savings
Banks usually do not cover the full cost of a property. You need to pay the remaining amount from your own savings. Keep some extra money for stamp duty, registration fees, legal fees, and other buying costs.
Documents Needed for a Pre-Launch Villa Loan
Keeping your documents ready can help make the home loan process faster.
- ID and Address Proof: PAN Card, Aadhaar Card, Passport, or Voter ID.
- Income Proof: Salary slips, bank statements, ITR, and business documents.
- Property Papers: Booking receipt, EOI, and allotment letter.
- Project Documents: Land ownership papers, layout approvals, and RERA registration details.
Step-by-Step Home Loan Process
Getting a pre-launch loan follows an easy step-by-step path from start to finish.
- Check Your Loan Budget: Work out how much you can safely borrow based on your monthly income and current loans before you start looking.
- Choose Your Villa: Pick a villa size, layout, and price that suit your budget and future needs.
- Check the Legal Papers: Make sure the project has clear land papers, required approvals, and valid RERA details.
- Apply for the Home Loan: Fill out the loan form and submit your ID proof, income documents, and villa booking papers.
- Bank Checks the Property: Bank lawyers and engineers visit the site to check land titles, boundary rules, and plan safety.
- Get Your Sanction Letter: The bank issues an official letter listing your total approved loan amount, interest rate, and terms.
- Sign the Agreements: Sign your loan contract and builder agreements after checking every fee, detail, and name.
- Get Milestone Payments: The bank pays cash directly to the builder in steps as construction moves forward.
Critical Buyer Safety Checklist
Before paying any booking amount for a pre-launch villa, check these important points:
- Check RERA Status: Check the project RERA number on your state’s official RERA website.
- Check Land Papers: Make sure the builder has clear land ownership and there are no legal issues.
- Check Approved Plans: Make sure the G+2 villa plans and layout are approved by the right authorities.
- Check Past Projects: Look at the builder’s previous projects to learn about their work and delivery record.
- Understand the Payment Plan: Know when and why you need to pay. Try to link payments to the work completed at the site.
How Much Loan Should You Take?
Do not borrow the maximum loan amount just because the bank offers it. Your total monthly EMIs should leave enough money for daily family expenses, savings, and emergency funds. Keeping extra cash on hand protects you if unexpected costs pop up during construction.
What If Your Bank Rejects the Project?
If your bank does not approve the project, ask them why. It could be due to missing documents or a delay in project approval. It does not always mean there is a problem with the project. You can also check other banks and housing finance companies to see if they offer loans for the project.
Common Mistakes to Avoid
- Booking Early: Never pay large cash deposits before getting a clear pre-approval letter from your bank.
- Ignoring Hidden Fees: Remember to factor in legal charges, loan processing fees, pre-EMI interest, and registration costs.
- Draining All Savings: Keep an emergency fund ready instead of spending every rupee on the down payment.
- Misreading Payment Stages: Make sure your money goes out based on real brick-and-mortar progress, not quick calendar dates.
Frequently Asked Questions
Yes, banks offer loans for pre-launch villas if the project passes all legal, title, and safety checks. Lenders check builder track records, layout approvals, and your personal income profile before approving the money.
Yes, RERA rules state that builders must register projects before taking bookings or running public ads. Always check the official RERA site to verify the project's state registration status.
No, bank checks protect the bank's money, not all your buyer rights. You must hire your own property lawyer to double-check land titles, agreements, and extra charges.
The bank sends money directly to the builder in parts as site work finishes. Each payment matches a set milestone, like completing the foundation, floor slabs, or wall plastering.
Yes, you can apply for an in-principle loan pre-approval based on your income, age, credit score, and job security. This helps you set a clear, safe budget before you shop for properties.